
Can You Argue with an Insurance Claims Adjuster
Yes, you can argue with an adjuster, and doing it with documentation instead of emotion is what actually moves a settlement.
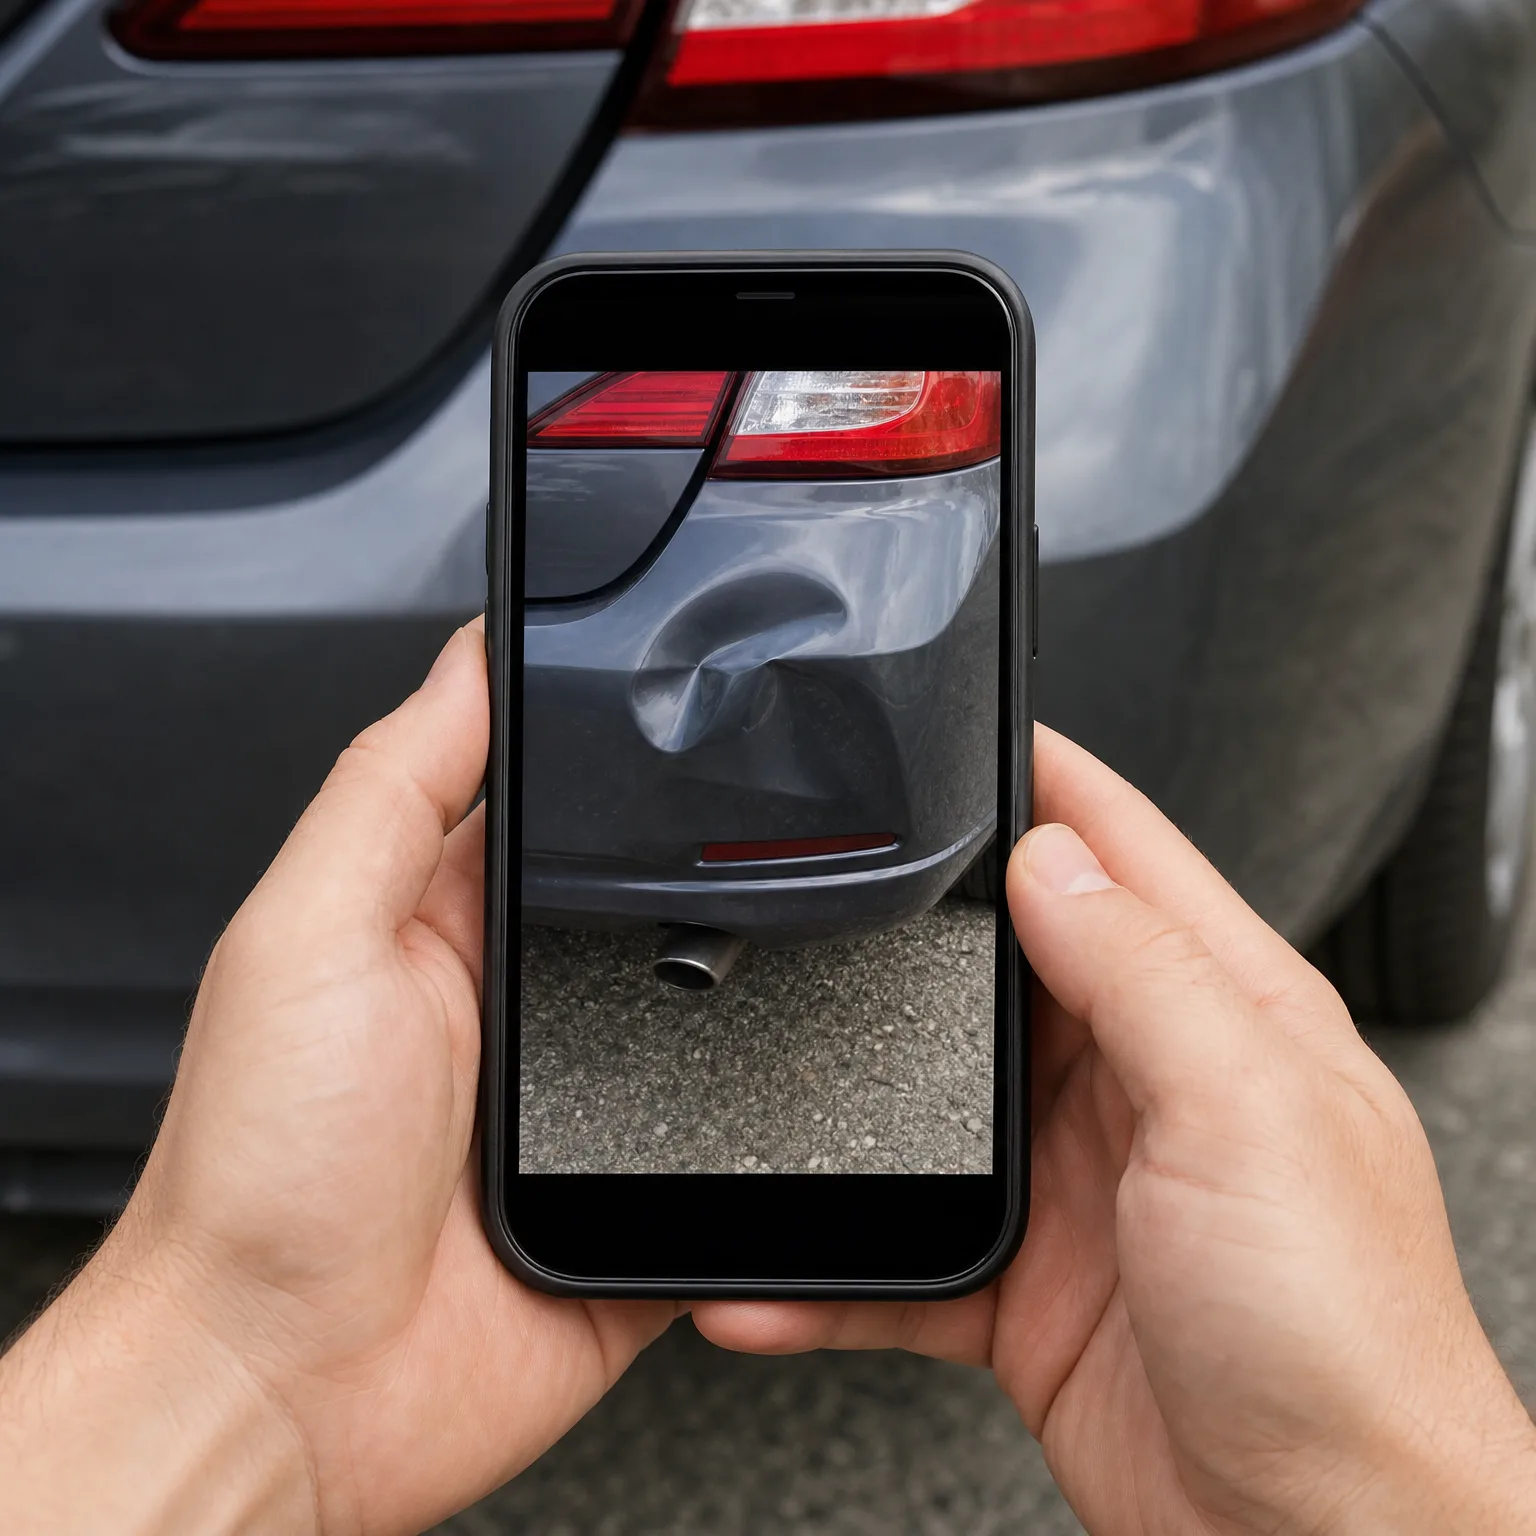
What makes an argument work with an adjuster
- Put it in writing Adjusters move faster on documented disputes than phone calls. Follow up every phone conversation with an email summarizing what was said, so there's a paper trail.
- Bring your own evidence An adjuster's first number is an opening position, not a final one. Counter it with repair estimates, comparable sales, or medical records that support a different figure.
- Know your policy language Your coverage terms decide what the adjuster can and can't deny. Pull your policy and read the specific section the adjuster is citing before you respond.
- Ask for the basis in writing If an adjuster denies or lowers a claim, you can request a written explanation. This forces them to justify the number and gives you something concrete to challenge.
- Escalate past the first adjuster Every adjuster has a supervisor, and every insurer has an appeals process. If you're not getting anywhere, ask to move up rather than repeating yourself to the same person.
A disagreement over a totaled car's value
A driver in their 80s was in a minor collision that left their older sedan undrivable. The insurer declared it a total loss and offered a payout based on a comparable vehicle search that pulled in cars with higher mileage and less equipment than what she actually owned. The number felt low, but she didn't know whether it was wrong or just how these things worked.
She asked the adjuster for the list of comparable vehicles used to set the value. Two of the four comparisons had noticeably more mileage and missing features her car had, like heated seats. She found three local listings for similar cars in similar condition and sent them along with her written response, asking the adjuster to revise the valuation. The adjuster adjusted the offer upward to reflect the better comparisons. It took about two weeks longer than if she'd simply accepted the first number, but the final payout was meaningfully closer to what the car was actually worth.
Whether to push back on the first offer
If you do
You ask for the adjuster's reasoning in writing, bring your own comparisons or estimates, and follow up by email. This usually takes a few extra weeks but often results in a revised number that better reflects your actual loss or damage.
If you don't
You accept the first number because it seems easier, and the claim closes quickly. If the offer was based on incomplete information, you may have settled for less than your policy actually owed you, and most insurers won't reopen a closed claim.
Once you know how to push back on a claim, compare quotes to see if another insurer handles claims the way you'd want.
Why adjusters expect pushback, and why it works
Adjusters are trained to settle claims efficiently, which means their first offer is often built from averages and automated valuation tools rather than a close look at your specific situation. This isn't dishonesty. It's a starting point meant to move claims through a large system quickly. The system expects that some claims will need a second look, and the adjuster has room to adjust when you give them a specific reason to.
What moves an adjuster isn't frustration or appeals to fairness. It's new information. A repair estimate from a shop they didn't use, a comparable vehicle they didn't include, a photo that shows damage they didn't account for. Adjusters respond to evidence because their own supervisors will ask them to justify any change, so the stronger your documentation, the easier it is for them to say yes.
There are limits to how far this goes. If your policy clearly excludes something, no amount of arguing changes that exclusion, and pushing on a clear denial just delays the inevitable. The useful fights are over valuation, interpretation of ambiguous policy language, or incomplete investigation, not over coverage that was never there to begin with.
How much room an adjuster has to move also depends on the insurer and the type of claim, so a straightforward glass claim won't have the same back and forth as a disputed liability claim after a collision. If you're unsure whether your disagreement is about facts or a hard exclusion, ask the adjuster directly which one applies.
An adjuster's first number is a starting point, not a verdict, so treat it that way.
How do I write an appeal letter to an insurance adjuster?
State clearly what you're disputing, cite the specific policy language or evidence that supports your position, and request a specific revised outcome. Keep it factual rather than emotional, attach your supporting documents like estimates or comparable listings, and ask for a written response by a specific date. A short, organized letter gets read more carefully than a long one, and it gives the adjuster exactly what they need to act on.
What happens if an adjuster and I can't agree on a settlement?
Most policies include a formal dispute process, often called appraisal or arbitration, that you can invoke when direct negotiation stalls. Check your policy for this clause since the exact steps and who pays for it vary by insurer and by state. If your policy doesn't spell out a process, you can file a complaint with your state's insurance regulator, who can review whether the claim was handled fairly.
Should I hire a public adjuster to negotiate for me?
It depends on the size and complexity of the claim. A public adjuster works on your behalf, usually for a fee tied to your settlement, and can be worth it for large or complicated losses like major home damage. For smaller or more straightforward claims, the fee can outweigh the benefit, so weigh the claim's size against the cost before hiring one.


