
Does a Comprehensive Claim Go Against You
A comprehensive claim usually costs you less than other claims do, but it can still nudge your renewal price up.
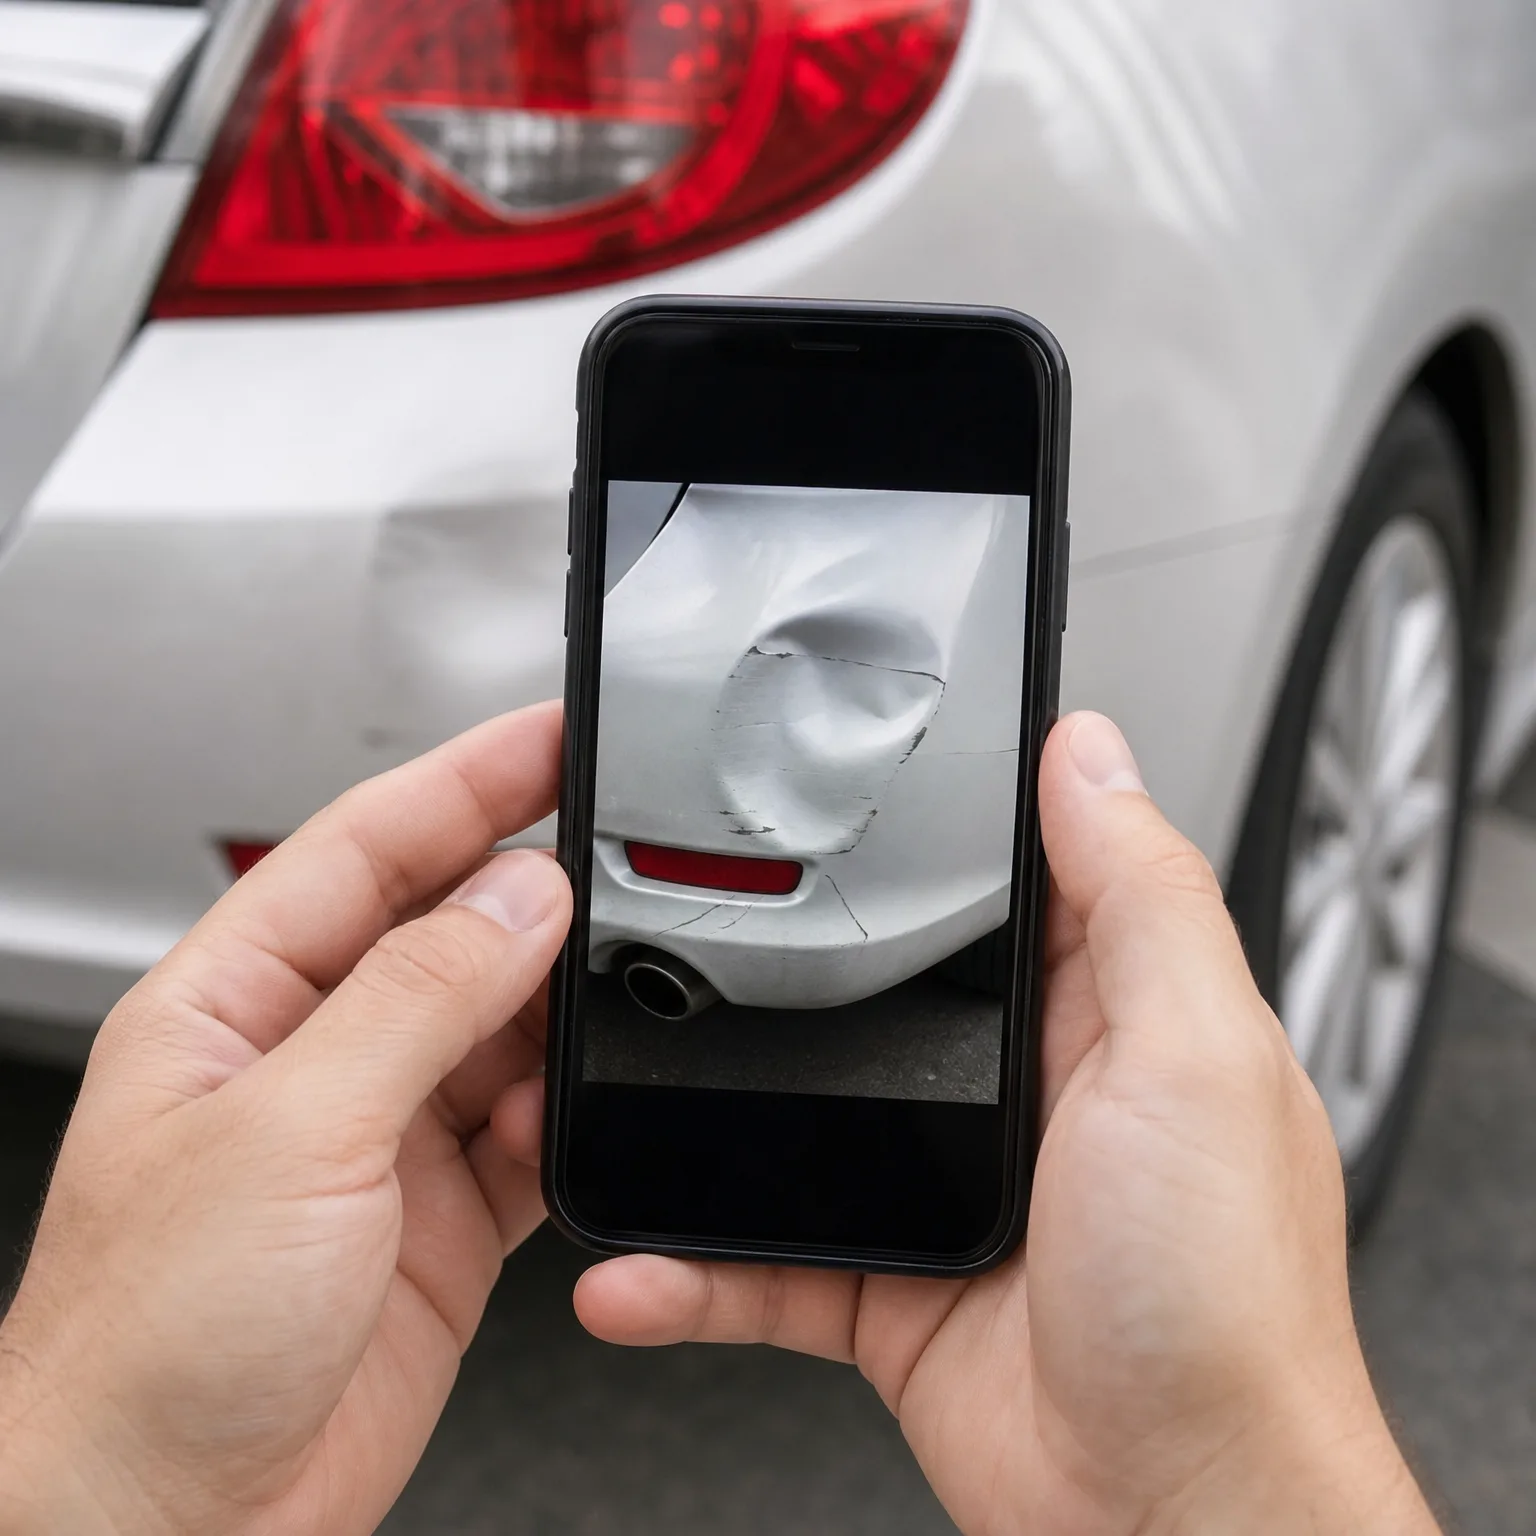
What actually happens after a comprehensive claim
- It's treated as no-fault Comprehensive covers things like weather, animals, or theft, not a crash you caused. Most insurers price it more gently than an at-fault accident, so check your policy's claim history rules to see how yours handles it.
- Your state matters here Some states limit how much a comprehensive claim can affect price, others leave it to the insurer. Call your agent or check your state's insurance department site to see what applies to you.
- Frequency matters most A single comprehensive claim rarely does much damage. Several in a short span can signal higher risk to an insurer, even if none were your fault.
- Insurers vary widely here Each company weighs comprehensive claims differently in their formula. Ask your agent directly how your insurer treats this type of claim before you decide whether to file.
- Not filing has its own cost If the repair is small, paying out of pocket may protect your record and your price. If it's large, the claim is likely still worth it even with a modest increase.
A hailstorm damages the car in the driveway
You wake up to find dents across the hood and roof after an overnight hailstorm. The repair estimate comes back higher than you expected, well past what feels comfortable to pay yourself, so you call your agent to ask how a comprehensive claim for storm damage would affect your renewal.
Your agent confirms it's a no-fault event and explains that your insurer treats weather claims more mildly than at-fault accidents. You file the claim, get the car repaired, and at renewal your price moves up slightly, not sharply. You decide it was worth it, since paying for the repairs yourself would have cost far more than the small increase did.
The claim isn't the risk. How often you file, and which insurer you're with, is what moves your price.
Now that you know how a comprehensive claim really affects your price, compare quotes to see where you stand.
Filing the comprehensive claim now
If you do
Your car gets repaired without draining your savings. Your renewal may rise a little, but most insurers treat this kind of claim gently since it wasn't your fault. You keep a record of one claim, which rarely causes lasting trouble on its own.
If you don't
You pay for repairs yourself and keep your claims history clean. This can help if you're close to a claims-free discount threshold, but you're covering a cost insurance exists for. If the damage is serious, skipping the claim may cost more than the increase would have.
Why comprehensive claims are treated more gently
Insurers price risk based on what a claim tells them about future claims. An at-fault accident suggests something about how you drive, so it carries more weight. A comprehensive claim, caused by weather, an animal, theft, or vandalism, says little about your driving. That's why most insurers treat it as a weaker signal of future risk.
Still, insurers aren't required to ignore it completely. Filing shows up in your claims history, and some underwriting systems factor in total claims regardless of fault. A company that prices heavily on claims frequency might raise your rate slightly even for a no-fault event, while another company might barely move the number at all.
State rules add another layer. Some states restrict how insurers can use comprehensive claims in pricing, treating them separately from at-fault claims by law. Other states leave this entirely to the insurer's own rules. This is why the same claim can affect two drivers differently depending on where they live and who they're insured with.
The exception worth watching for is repetition. One comprehensive claim is unlikely to change much. Multiple claims in a short window, even unrelated ones like a cracked windshield followed by storm damage, can start to look like a pattern an insurer prices around. That's less about fault and more about how often you're asking the insurer to pay.



