
What Happens if Insurance Finds Out You Lied
If an insurer finds out you lied, the usual result is a canceled or voided policy and a denied claim, not forgiveness.

What happens once the lie is confirmed
- Your claim gets denied If the lie relates to the accident or the risk involved, the insurer won't pay for damage or injuries. You're left covering those costs yourself, right when you can least afford it.
- Your policy can be voided The insurer can treat the policy as if it never existed, which erases any claims paid since it started. Expect a written notice explaining the reason and the date it takes effect.
- Future coverage gets harder A canceled or voided policy shows up when other insurers check your history. You should expect higher offers or flat refusals for several years afterward.
- Your license may be affected If the state learns your coverage was invalid, it can treat you as uninsured, which carries its own penalties. Check with your state's motor vehicle office about what a lapse like this triggers.
- Some lies cost more than others A lie about address or mileage is treated differently than one about a prior accident or who was driving. Be honest about anything tied directly to risk or fault, since that's where insurers look hardest.
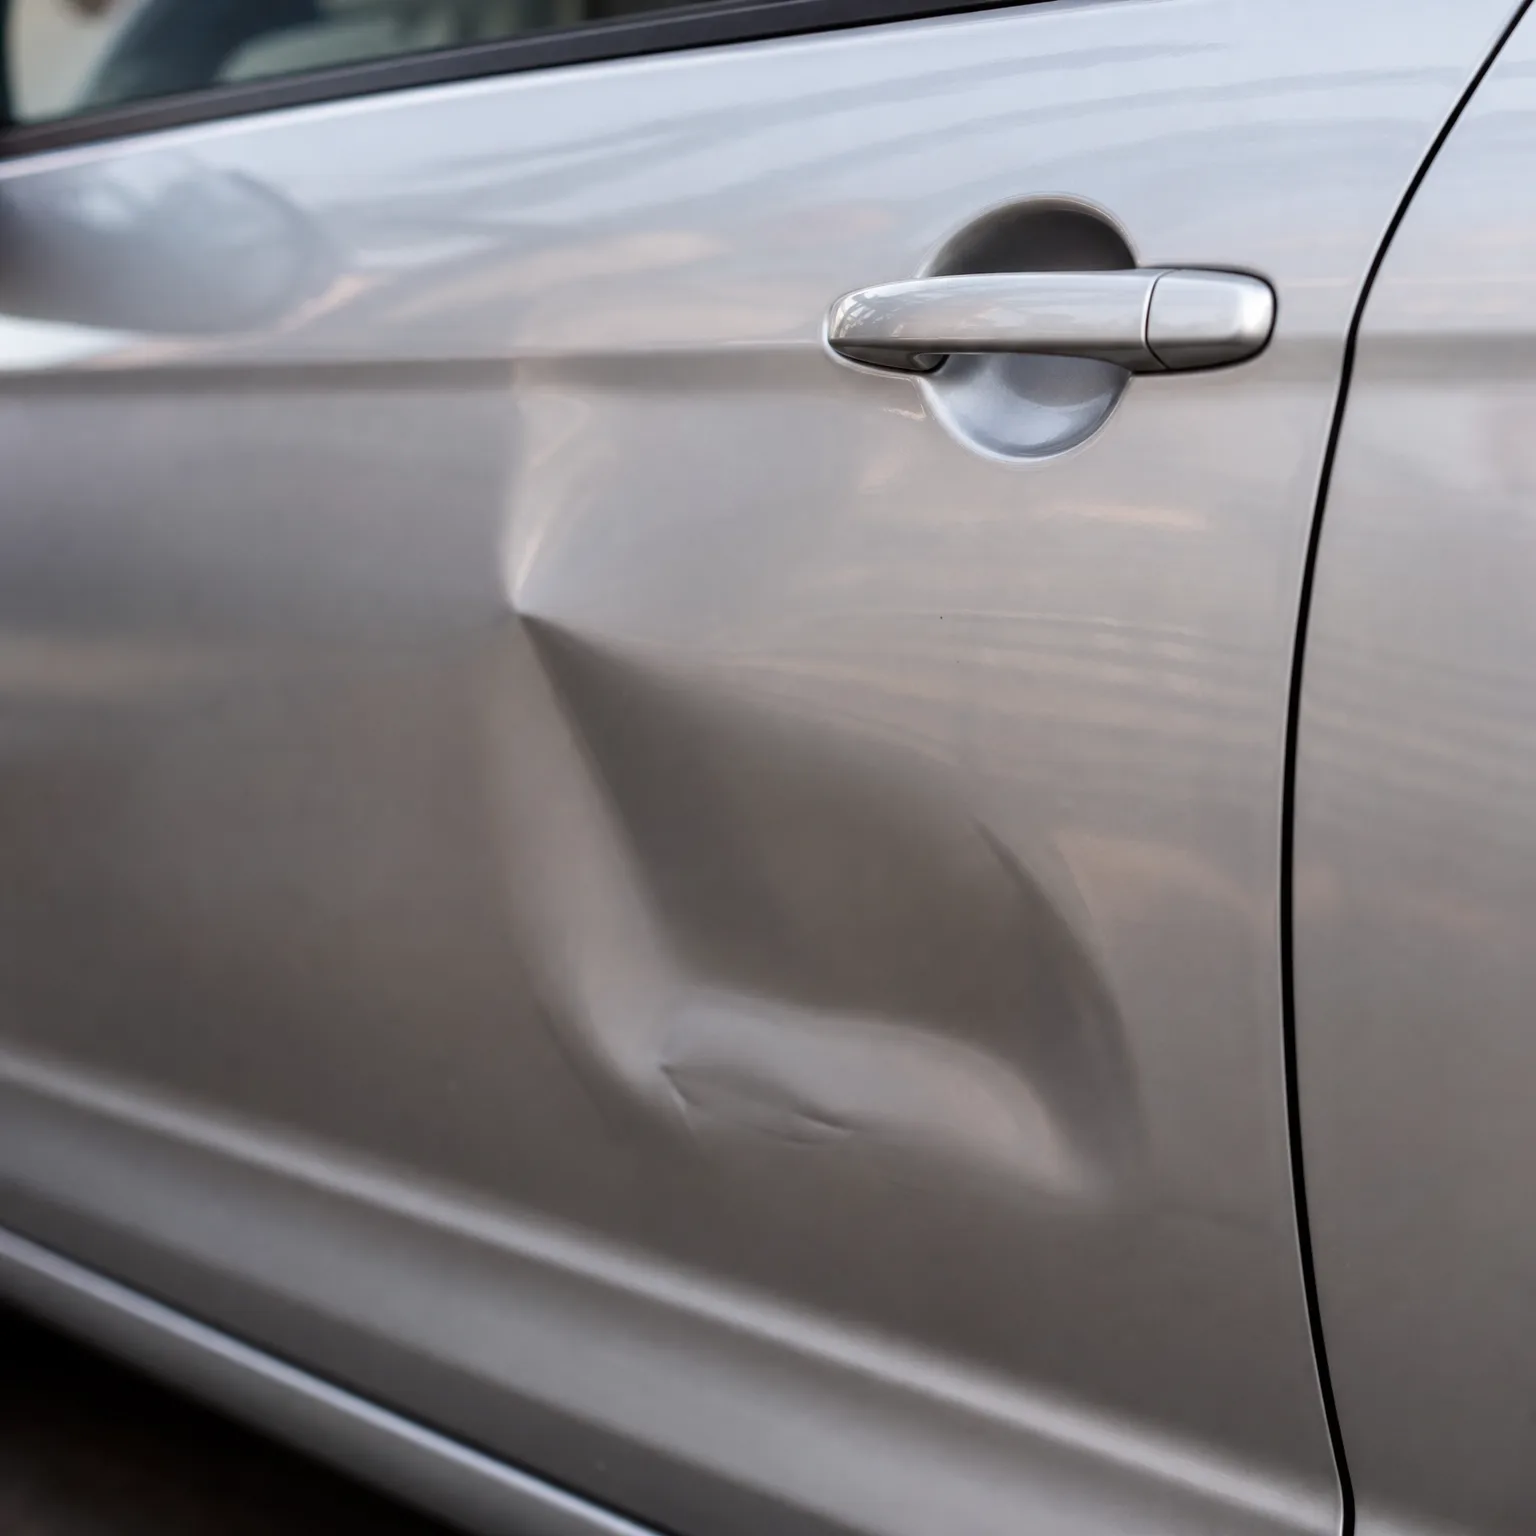
A driver who left out a recent fender bender
A driver renewing coverage didn't mention a small accident from the year before, thinking it wouldn't matter since no one was hurt and the damage was minor. The insurer later pulled the state's accident record while reviewing a new claim and found the gap between what was reported and what actually happened.
The insurer denied the new claim, pointing to the misrepresentation on the file, and sent notice that the policy was being voided retroactively. The driver had to pay for the new accident's damage directly and then shop for coverage with a lapse and a voided policy on record. Rates came back noticeably higher, and it took a few years of clean driving before offers looked normal again. The lesson wasn't that the first accident was serious, it was that leaving it off the form turned a small problem into a lasting one.
The danger was never the fact you left out, it's the gap that fact creates once the insurer checks.
Once you know what's actually on your record, you can compare quotes knowing exactly what to disclose.
Whether you correct the record before renewing
If you do
You call the insurer, explain the detail you left out, and ask how it affects your policy. They may adjust your rate or flag the file, but your coverage stays valid and any future claim gets paid without a fight.
If you don't
You renew as is, hoping it won't come up. If a claim or a records check later reveals it, the insurer can deny the claim, void the policy, and leave you paying for damages and a canceled history on your own.
Why insurers treat this so seriously
An insurance policy is built on the information you give at the start. The insurer sets your price and decides whether to cover you at all based on what you report about your driving, your health, your vehicle, and your history. When that information turns out to be false, the insurer argues it never agreed to the deal you think you have, because the deal was based on facts that weren't true.
This is why the response is usually bigger than a simple denial. Insurers don't just refuse one claim, they often go back to the start of the policy and treat it as void, because the misrepresentation affected every decision made since then. That protects the insurer from having accepted risk it wouldn't have taken on if it had known the truth.
How strict the response is depends on how central the lie was. A lie about something that had little bearing on risk, like a middle name spelled wrong, is treated very differently from a lie about who was driving at the time of a crash or whether you'd had a license suspension. Insurers and state regulators both draw a line between honest mistakes and intentional misstatements, and that line matters for what happens next.
State rules also shape the details. Some states give insurers more room to void a policy outright, while others require the insurer to show the lie was material before taking that step. Check with your state's insurance department or the policy's own fraud language to see which standard applies where you live, since it changes how much protection you have if a mistake turns out to be the issue instead of a lie.
Can I fix a mistake on my insurance application after the fact?
Yes, and doing it before a claim comes up is far better than waiting. Call your insurer directly, explain what was wrong, and ask for it to be corrected in writing. Insurers generally treat a voluntary correction much more kindly than one they uncover themselves. What changes the outcome is timing, so do this as soon as you realize the error, not after an accident forces the issue.
Does a lapsed or voided policy affect my driver's license?
It can, depending on your state. Many states require continuous proof of insurance, and a voided policy can look like a lapse in coverage to the motor vehicle department. That can lead to fines, suspension, or reinstatement fees separate from anything the insurer does. Check your state's requirements directly, since the penalties and the process for clearing them vary widely.
How long does a canceled policy stay on my record?
It typically stays visible to insurers for several years, though the exact length depends on the reporting database your state and insurers use. During that time, expect higher quotes and more questions on applications. What shortens the effect is a clean history afterward, since steady, accurate coverage over time gradually outweighs the earlier cancellation in how insurers price you.


